Dr. Reddy’s Laboratories Limited
NSE: DRREDDY | BSE: 500124 | Sector: Pharmaceuticals | Large-Cap
Business Overview
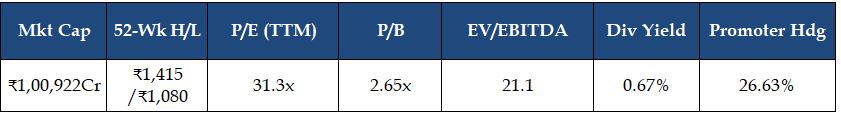
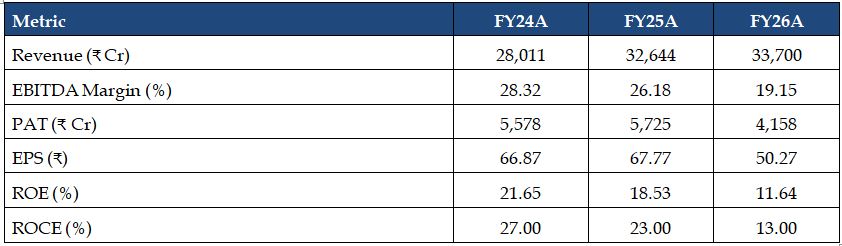
Dr. Reddy’s Laboratories Limited is a Hyderabad-based integrated global pharmaceutical company, a Nifty 50 constituent and ranked No. 10 in the Indian Pharmaceutical Market. It operates through three segments: Global Generics (North America, Europe, India and Emerging Markets), Pharmaceutical Services & Active Ingredients (APIs and CDMO), and Others (Aurigene oncology and proprietary products). FY26 consolidated revenue was a record ₹33,700 Cr (+3.2% YoY), with India (+16%) and Emerging Markets (+23%) offsetting a sharp fall in North America on lower lenalidomide sales, while consolidated PAT dropped to ₹4,158 Cr from ₹5,725 Cr on one-offs. Q1 FY27 (Jun 2026) revenue was ₹8,100 Cr with an operating margin of 11% and PAT of ₹436 Cr, still well below the 25–28% margins of FY24–FY25. It reported TTM revenue of around ₹33,228 Cr and TTM PAT of ₹3,183 Cr. Promoter holding is 26.63%, with DIIs at 31.75% and FIIs at 20.67% (Jun 2026). The company is not debt-free, with borrowings of ₹7,734 Cr at Mar 2026 against reserves of ₹37,808 Cr. Q2 FY27 results are due on 23 October 2026.
Financial Summary
Technical Snapshot
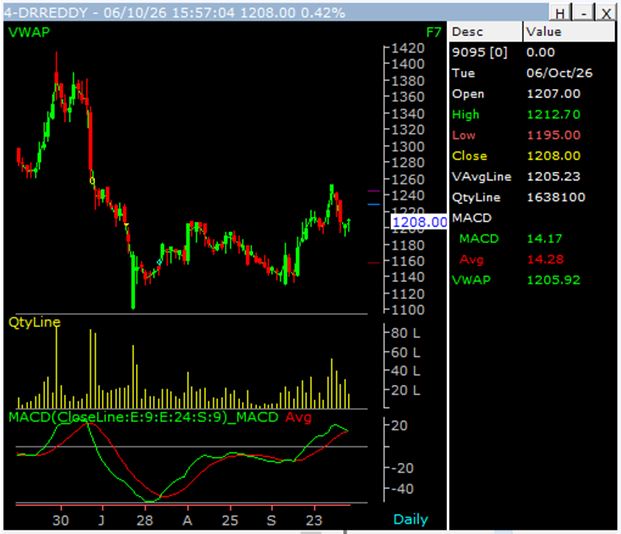
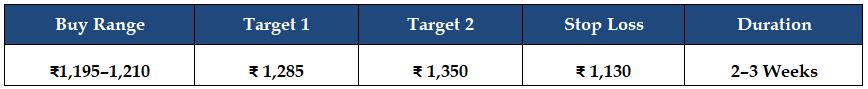
Dr. Reddy’s closed at ₹1,203 on 5 October, about 15% below its 52-week high of ₹1,415 and about 11% above the 52-week low of ₹1,080. The stock is trading above its 20- and 50-day moving averages but below the 100- and 200-day averages, which points to a bounce within a broader consolidation rather than a confirmed trend reversal. The ₹1,150–1,180 zone is the key demand area; ₹1,260 and ₹1,320 are the nearest resistance levels. Near-term fundamentals are weak (Q1 FY27 operating margin 11% vs 25–28% in FY24–FY25), so this is a technical/momentum setup, not a valuation call. Targets are projected over a 2–3 weeks horizon.